10/19/26
When you hear the words financial legacy, what comes to mind? Maybe it’s leaving money to your children, owning a home, or having enough saved to help your family in the future. I used to think a financial legacy was something you built over your lifetime and left behind when you’re gone. But the more I learn about financial planning, the more I realize that it’s about so much more than just money. It’s also about the choices we make today and how we prepare for tomorrow and the generations to come.
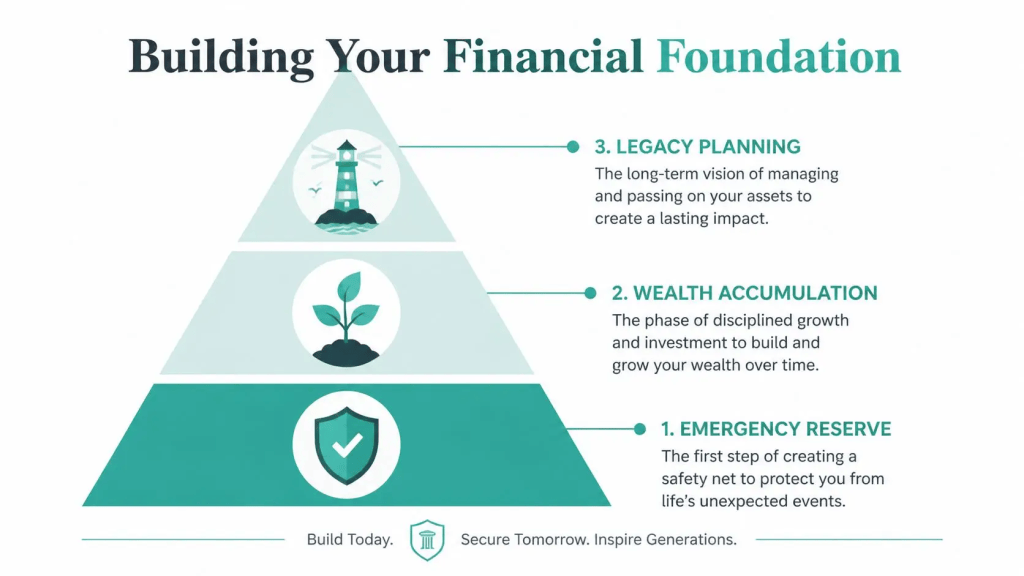
One part of leaving a legacy is getting your finances organized. This means knowing where your money goes, paying down debt, building savings, and finding ways to grow your money over time. Saving is a great place to start, but have you ever thought about, what if your money could work for you?
Depending on your goals, there may be different strategies worth exploring. For example, certain indexed financial products offer the opportunity to earn interest based on the performance of a market index, such as the S&P 500, while protecting against losses caused by negative index performance under the product’s terms. These products have limitations, costs, and rules to understand, but learning about your options can help you make more informed decisions about your financial future.
Another part of leaving a legacy is preparing for the unexpected. Have you ever thought about what would happen to your money, assets, or business if something happened to you? This is where estate planning comes in. Creating a will, reviewing who is listed as a beneficiary on your accounts, and considering life insurance are all ways to prepare for the people you care about. These conversations might not be the most comfortable, but having a plan in place can make things easier for your loved ones down the road.
And finally, a financial legacy is also about what you teach others. Think about how you learned to save money, manage bills, or make financial decisions. Maybe someone taught you, or maybe you had to figure it out on your own. Sharing what you’ve learned with the people around you can make a difference. Teaching someone how to save, understand debt, or plan for the future can be just as valuable as leaving them money.
At the end of the day, you don’t need to be wealthy or have everything figured out to start building a financial legacy. It’s about making thoughtful decisions with what you have, learning about ways to grow and protect your money, and preparing for the people who matter most to you. You don’t have to figure it all out alone, either. Talking with a financial professional can help you understand your options and find out what may fit your goals.
Something to think about: If someone you love had to manage your financial affairs tomorrow, would they know where to start? If the answer is no, that’s okay. It just means you have a place to begin.
Your legacy starts today. Small steps now can make a lasting difference for you and the people you love.
BOOK HERE for a FREE 1:1 CONSULTATION!


Leave a Reply